


Inside &Partners’ approach to estate planning
A case study in wealth transfer


Ask someone whether they’ve completed their estate plan, and they’ll point to a will or trust. Often, that’s only part of it. Many of a family’s largest assets — retirement accounts, life insurance, annuities, a transfer-on-death account — pass by beneficiary designation, not through estate documents, and often represent most of a household’s net worth. That raises a question most people never ask: Who is coordinating my estate?
The instinct is to hand estate planning to an attorney. Attorneys draft the documents but then often disengage. Neither they nor a CPA has what the financial advisor has: an ongoing, full-balance-sheet view of a client’s assets, titling, beneficiary designations, and life goals — the view that makes coordination possible.
That coordination matters most when the law gets local. Most people focus on the current federal exemption — $15 million per person in 2026, portable between spouses, effectively $30 million for a couple — and assume they’re safe. State exemptions, however, can change the equation. New York’s current $7.35 million exemption isn’t portable between spouses, and past the threshold of $7.72 million, it disappears entirely — the estate is taxed from the first dollar. A couple with meaningful wealth can carry that exposure unknowingly, even with a well-drafted plan. Identifying that risk takes an advisor willing to ask what most people avoid. Claire Coombs, Partner and Wealth Advisor at Heritage Lake Advisors | &Partners, makes it routine. “A big part of my job is reminding people they’re not going to live forever,” she says. She asks about a client’s estate plan as naturally as their portfolio allocation. “Taking the time to do this right is a love letter to your family,” she says. Done well, estate planning spares loved ones from untangling financial and legal loose ends while navigating grief. This isn’t a specialized practice at &Partners, as &Partners advisors often coordinate this process with the client’s attorney and illustrate it with eMoney to make the exposure concrete.
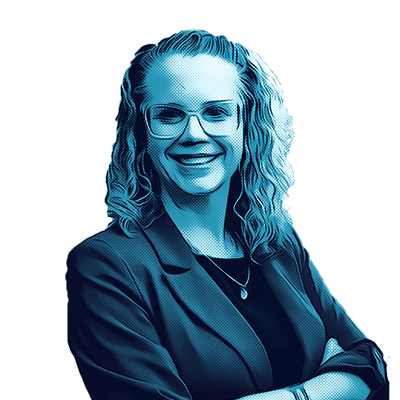

Taking the time to do this right is a love letter to your family. Done well, estate planning spares loved ones from untangling financial and legal loose ends while navigating grief.
Claire Coombs
Partner and Wealth Advisor at Heritage Lake Advisors | &Partners
As an advisor to high-net-worth clients in New York, Claire frequently encounters complex estate-planning situations. Many involve couples whose combined assets exceed twice the individual estate tax exemption, with wealth heavily concentrated on one spouse’s side of the balance sheet and no adequate estate plan in place. Without proper planning, the first spouse’s death could waste New York’s nonportable exemption if assets pass directly to the surviving spouse rather than to a credit shelter trust — potentially exposing the estate to a largely avoidable tax bill.
Claire’s team works to rebalance holdings between spouses and coordinates with estate attorneys to establish pour-over wills and revocable living trusts with an A/B, or bypass trust, structure. This allows the first spouse to die to use their New York estate tax exemption rather than lose it, while preserving the surviving spouse’s access to the trust assets under standard HEMS provisions. In some cases, funding generation-skipping trusts can also help move assets and future appreciation outside the taxable estate without triggering federal gift tax.
The result of her thoughtful planning: potentially significant reductions in taxes and expenses, allowing more wealth to pass to clients’ heirs. The multimillion-dollar difference represents the potential cost of an estate plan that was never fully coordinated.
Any advisor can make this part of every client relationship — asking when estate documents were last reviewed, pulling the full balance sheet, and checking whether titling and beneficiaries match the plan. Advisors who skip this step miss a potential opportunity to deepen relationships and better serve clients. The ones who make it routine are appreciated by clients and celebrated by the next generation.
Matt Doran is Leader of Advanced Planning at &Partners, and brings over 20 years of experience as a CFP professional to support advisors and clients with sophisticated financial and tax strategies. He’s previously held holistic planning roles at Sage Wealth Planning and Edward Jones. Matt holds a master’s in taxation and an estate planning certificate from Villanova University.
Claire (Clarissa) Coombs, Partner and Wealth Advisor at Heritage Lake Advisors | &Partners, has over 25 years of experience helping clients pursue financial well-being through clear guidance aligned with their values and goals. She holds a BA from the University of Kentucky and FINRA Series 7 and 66 registrations with 38 state licenses.
Reprinted with permission from AdvisorHub.
&Partners does not render legal or tax advice. Any examples are hypothetical and for discussion purposes only. It is not intended to represent any specific strategy or outcome. Individual experiences referenced above may not reflect the future experience of any client. The planning process discussed may not be appropriate for your personal situation, even if it is similar to the example presented.
Related content
“The Future of Advisor Value” with Matt Doran and Duncan MacPherson
Matt Doran joins Duncan MacPherson on his podcast, Always On for Financial Advisors to discuss artificial intelligence, alternative investments, and financial advisors’ evolving role.
Trump Accounts: Are they right for your family?
What are Trump Accounts (530A IRAs)? And how do these investment accounts for children compare to other, popular accounts? Our article and comparison chart explain.